Car Title Loans Toronto vs. Bank Loans: What Borrowers Should Know

How Ontario Car Equity Loans Can Help Manage Rising Living Costs
August 4, 2026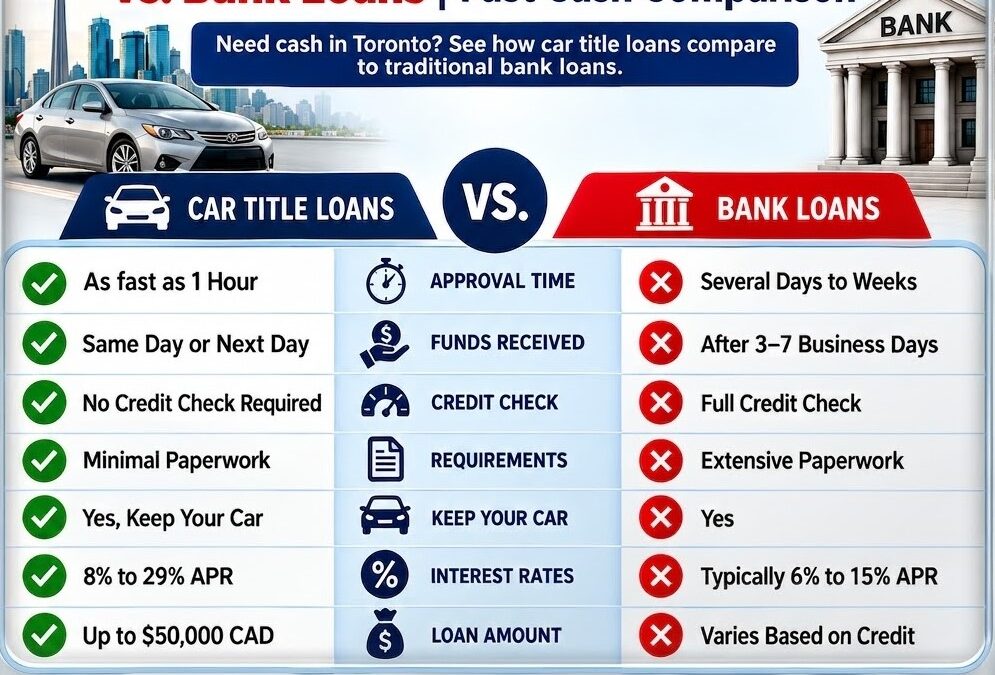
A car repair bill arrives on a Tuesday. Rent is due Friday. Your credit score isn’t what it used to be, and traditional bank financing may take longer to review, depending on the lender and application. This is the moment most people start comparing Car Title Loans in Toronto against traditional bank loans, and the two paths look nothing alike once you look into the details. Speed, credit requirements, and how much you can borrow all shift depending on which route you take, so it’s worth understanding the mechanics before you sign anything.
How Car Title Loans Toronto Options Compare to Traditional Bank Financing
Traditional bank lenders generally review factors such as income, credit history, existing debt, and other financial information. That approach may work when you have time to wait for a decision, but it can be less practical when you need access to funds sooner. Vehicle-backed lending flips the priority. Instead of leading with your credit score, it leads with the equity sitting in your car, truck, or SUV. Someone who’s had a rough couple of years financially but owns their vehicle outright may find that a vehicle-backed financing option provides another route to consider when traditional financing is not suitable. It’s not a replacement for banking. It’s a different tool for a problem. This type of vehicle collateral loan can be considered when access to funds is more urgent.
Approval Speed: Why Faster Timelines Matter to Borrowers
Traditional financing timelines can vary depending on the lender, documentation, and review process. That’s the reality with a lot of traditional personal loans though, especially once you factor in appointment scheduling and paperwork bouncing back and forth between departments. The vehicle backed process moves faster because it skips most of that. Same-day funding may be available for approved applicants once the required documents, vehicle assessment, and verification are completed. For anyone dealing with a deadline that won’t move, that difference in speed can matter more than almost anything else on this list. For borrowers searching for same day car title loans, document verification and approval requirements still need to be completed first
Interest Rates and Repayment Terms Explained
Rates and repayment terms shift depending on a few key factors, so here’s the breakdown in short form. Understanding the car title loan rates and repayment costs beforehand can help you decide whether the financing fits your budget
- Interest rates range from 8% to 29% APR
- Your rate depends on vehicle value, loan amount, and overall application
- Banks often provide lower rates, but reserve them for applicants with the strongest credit profiles
- Repayment terms run from 61 days up to 72 months
- Longer terms let you pick a schedule that fits your paycheck instead of one rigid structure
- Example: borrow $10,000 CAD over 48 months
- Lower tier rate: monthly payments start around $244.13
- 29% APR cap: monthly payments reach $352.41
Credit Requirements and Why They Differ So Much
A bank loan application may consider your credit history alongside income, existing debt and other parts of your financial profile. Past credit challenges may make some traditional financing options more difficult to qualify for, no matter how much equity you might have sitting in your driveway. No credit check is required for this financing option. Eligibility will be based on the value of the vehicle, availability of equity, ownership information and other application requirements.
That doesn’t mean everyone gets approved automatically since things like vehicle condition, ownership, and existing liens still factor in. What it does mean is that a lower credit score won’t necessarily be the thing that shuts you out. This can make bad credit car loans an option worth researching for some vehicle owners.
Loan Amounts and Flexibility Across Both Options
Borrowing power looks different depending on where you go. Banks run your income and credit tier through a formula, and sometimes that formula spits out a number smaller than what you need.
With a vehicle backed structure, the ceiling moves with your equity instead. Eligible borrowers may be able to access up to $50,000 CAD, depending on vehicle value, available equity, condition, and other eligibility requirements. A Ontario Vehicle Loan shaped this way tends to give people more room to match the loan to the actual expense in front of them, whether that’s a home repair, a medical bill, or clearing off higher interest debt.
Comparison Table: Car Title Loans vs Bank Loans
| Feature | Car Title Loans (Toronto) | Traditional Bank Loans |
| Approval Speed | May be available same day once documents are confirmed | Typically several days to a few weeks |
| Credit Requirement | No credit check required; eligibility based on vehicle value, equity, ownership, and other requirements. | Credit history and financial profile are typically reviewed. |
| Interest Rate Range | 8% to 29% APR | It varies widely, from lower to top tier credit only |
| Repayment Term | 61 days to 72 months | These are fixed term, often 12 to 60 months |
| Loan Amount | The loan amount is based on vehicle equity | Based on income and credit tier |
| Collateral Required | Vehicle equity | May be secured or unsecured depending on the loan product. |
| Application Process | Vehicle inspection and ownership verification | Extensive documentation and credit review |
Which Option Fits Your Financial Situation?
Timing usually decides this more than anything else. If your credit is solid and you can afford to wait out a longer approval window, a bank product might genuinely be the better fit, especially with a fixed repayment structure you can plan around.
But if your timeline is tight, your credit history has some dents in it, or you prefer to review repayment options that may better match your budget, a Vehicle Equity Loans Ontario option is worth a closer look. Whichever direction you go, only borrow what you can comfortably repay each month. That single decision matters more in the long run than how fast your funds arrive.
Frequently Asked Questions
Are car title loans in Toronto harder to qualify for than bank loans?
No, they work differently. Your credit score isn’t required. No credit score needed. It’s your car, your equity, your ownership documents.
Can I still drive my car after using it as collateral?
Yes, you keep the car with you and drive it like normal while paying off the loan.
Is same day funding guaranteed?
There is no guarantee of same-day approval. It really comes down to how fast your paperwork gets checked.
What happens if my credit score is low?
There is no requirement of credit score. The loan is based on your vehicle and the other details in your application, not your score.
How much can I borrow against my vehicle?
Loans go up to $50,000 CAD, depending on what your car is worth and its condition.
Conclusion
A bank loan and a car title loan aren’t competing for the same borrower. A bank provides you a loan when you have a strong credit profile, don’t need funds immediately, and can qualify for terms that fit your budget. Vehicle-based financing may provide options for eligible borrowers who need access to funds and have available vehicle equity. If your car has equity sitting in it and your timeline won’t wait, Car Title Loans in Toronto give you a way forward that does not require a credit check and is assessed based on factors such as vehicle value, available equity, and eligibility requirements. Just make sure whatever you borrow fits comfortably into your monthly budget, and go through the repayment terms line by line before you sign.
If you’re considering this type of financing, Approve Loan Now can help you understand your vehicle’s available equity, eligibility requirements, and the financing options that may be available. Contact us at 1-844-452-4125 to know more.